There are no two identical Clients for an insurer. Age, lifestyle, health condition, habits, and even certain physical indicators may affect the level of risk. That is why, when arranging insurance, the company asks the Client to provide certain information about themselves.
Among such data are height and weight. At first glance, this may seem like overly meticulous data collection, but in practice, it helps to assess a person’s individual health characteristics more accurately and to establish fair conditions for insurance protection. For this purpose, the body mass index (BMI) is used — one of the most widespread indicators in the world for assessing the ratio of weight to height.
Why does BMI remain an important tool for insurers, which of its advantages should not be underestimated, and why is it important to provide accurate personal data when completing an insurance questionnaire?
We explain all of this in this blog.
What Is Body Mass Index and Why Is It Needed?
Body mass index (BMI) is an indicator that helps assess the ratio of a person’s weight to their height. It is not a diagnosis in itself and does not make it possible to determine a person’s health condition with absolute accuracy. However, BMI has been used for many decades in medicine and insurance as one of the basic tools for assessing potential health risks.
The reason is that numerous studies have identified a link between excess body weight and an increased risk of developing cardiovascular diseases, type 2 diabetes, certain types of cancer, and other chronic conditions. At the same time, being underweight may also indicate certain risks to the body. That is why BMI helps specialists gain an initial understanding of possible risk factors.
In insurance, BMI is used as one of the elements in assessing a client’s health condition. When completing an insurance application, a person provides their height and weight, after which the system automatically calculates the relevant indicator. This makes it possible to assess individual risks more accurately and establish the terms of insurance protection.
At the same time, modern medicine increasingly emphasizes that BMI is a useful reference point, but it does not provide a complete picture of a person’s health condition. After all, people with the same BMI can differ significantly in terms of physical fitness, lifestyle, and their actual level of health risk. This is what we will discuss next.
Why Is BMI Not the Whole Story?
Although body mass index has been used for many years in medicine and insurance as one of the risk indicators, this measure has its limitations.
For example, two people may have the same BMI but differ significantly in terms of their health condition. One may be an athlete with well-developed muscle mass, while the other may be a person with excess body fat and a low level of physical activity. The BMI formula does not distinguish what the body mass is made up of, so it does not always provide a complete picture.
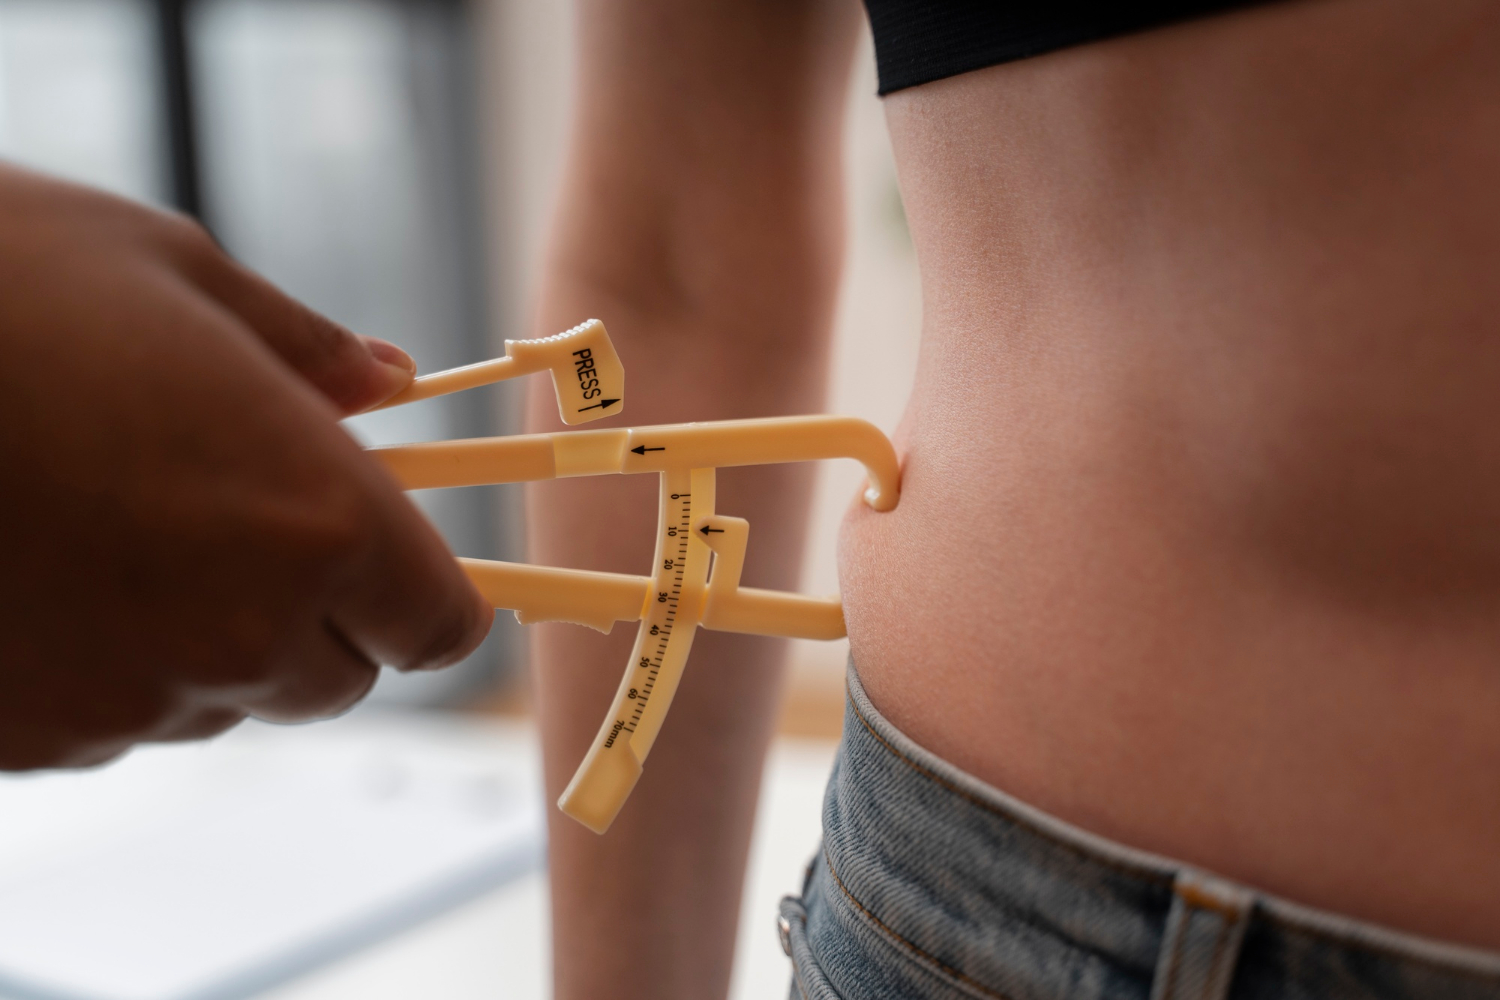
That is why scientists are increasingly focusing not only on a person’s weight, but also on how exactly fat is distributed throughout the body. Particular interest is being paid to so-called abdominal or visceral fat — fat deposits in the abdominal area around the internal organs. Studies show that it is more strongly associated with the risk of cardiovascular diseases, metabolic disorders, and diabetes.
This was confirmed by a large-scale study published in the Journal of the American College of Cardiology. Scientists followed more than 250,000 adults for approximately 20 years and concluded that waist circumference and the waist-to-hip ratio provide additional information about the risk of cardiovascular diseases that cannot always be identified using BMI alone.
Moreover, among people with normal or increased body weight, a large waist circumference was associated with a significantly higher risk of heart attack, stroke, and heart failure. At the same time, among some people who, according to BMI, were classified as having obesity but had a relatively small waist circumference, the risks were found to be close to those of people with a normal BMI.
This does not mean that BMI is outdated or has lost its value. On the contrary, it remains a simple and useful tool for the initial assessment of risks. However, modern research shows that, for a more complete understanding of a person’s health condition, it is important to take other indicators into account as well, including body composition characteristics and the distribution of fat tissue in the body.
How Does This Work When Arranging Insurance with TAS life?
When completing an insurance application, the Client indicates their height and weight. Based on this data, the system automatically calculates the relevant indicator and determines its percentile for the person’s sex and age. This helps to understand how typical the resulting value is for people of the respective sex and age group.
The result obtained is one of the factors taken into account when assessing risk. If the indicator is within the normal range, it does not affect the cost of insurance. If the value falls outside the established limits, a surcharge may be applied to the insurance premium.
This approach makes it possible to assess risks more individually rather than applying the same conditions to all Clients. After all, people with different health conditions and different risk factors may require different levels of insurance protection.
At the same time, height and weight are only part of the overall picture. Other information provided in the insurance application may also be taken into account when making a decision.
What If You Enter Your Weight “With a Little Optimism”?
Many people have, at least once in their lives, mentally subtracted a few kilograms from their weight or added a few centimeters to their height. However, when arranging insurance, such an “adjustment for the desired result” may not work in the Client’s favor.
The reason is that the insurance company calculates risks based on the information provided by the person. If the data in the questionnaire differs significantly from the actual data, the risk assessment may also turn out to be inaccurate.
Therefore, the best solution is to provide your actual height and weight at the time of completing the application. This helps establish correct insurance conditions and avoid misunderstandings in the future.
Ultimately, insurance works best when both the Client and the insurance company have an equally accurate understanding of the initial data. That is why honesty when answering the questions in the questionnaire is no less important than carefully familiarizing yourself with the terms of the insurance contract.